
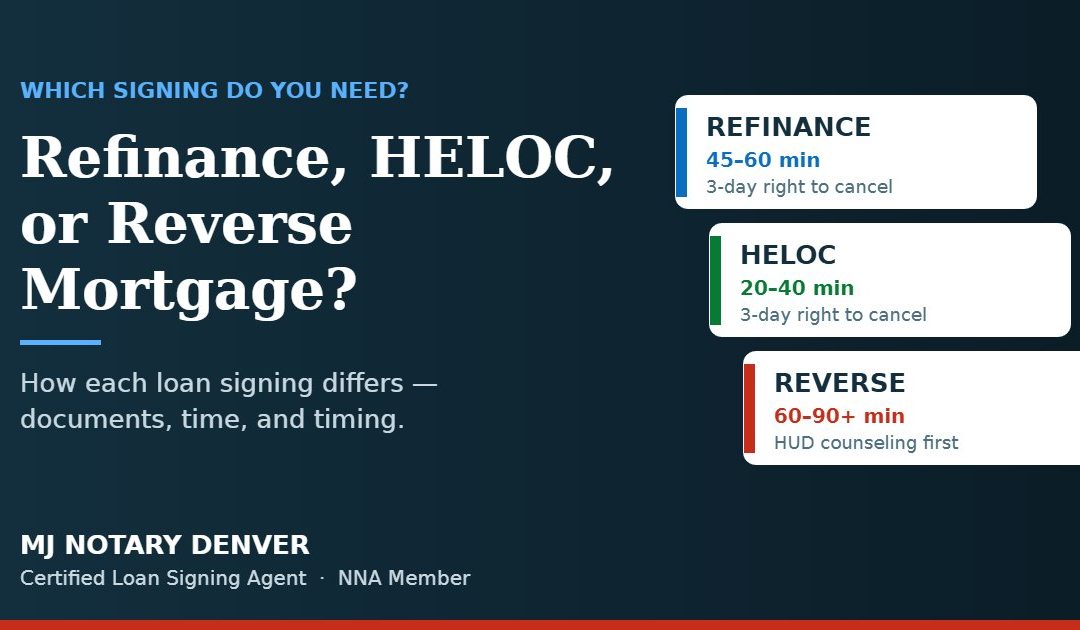
The signing you need depends on the loan. A refinance replaces your current mortgage with a full package and a three-business-day right to cancel. A HELOC adds a line of credit with a shorter package and the same right to cancel. A reverse mortgage lets homeowners 62 and older draw on their equity; it has the longest package and requires HUD-approved counseling before closing.
“We just need you to sign the package” sounds the same whether you are refinancing, opening a home equity line, or closing a reverse mortgage. It isn’t. Each loan type comes with a different set of documents, a different appointment length, and different rules about what happens after you sign. This guide explains how the three most common homeowner signings differ, so you know what to expect before the notary arrives.
It is part of our complete guide to loan signing agents in Denver. For the appointment itself, see the loan signing process, step by step.
Refinance vs. HELOC vs. Reverse Mortgage Signing: Side by Side
| Signing type | What it does | Typical time | 3-day right to cancel? |
|---|---|---|---|
| Refinance | Replaces your current mortgage (new rate, term, or cash out) | 45–60 min | Yes, on a primary home |
| HELOC | Adds a revolving line of credit secured by your equity | 20–40 min | Yes, on a primary home |
| Reverse mortgage | Converts equity to cash or income for owners 62+ | 60–90+ min | Generally yes (not when used to buy) |
| Purchase | Finances a home you are buying | 45–75 min | No |
Times are typical ranges, not guarantees. A borrower who reads every page closely — which is always your right — will take longer, and that is fine.
Which Signing Is Yours?
If you are not sure what kind of loan your package is, your Closing Disclosure will say. Or follow the quick decision path below.
Refinance Signings
A refinance pays off your existing mortgage with a new one. People refinance to lower their rate, change the loan term, remove mortgage insurance, or take cash out of their equity. From the signing table, all of these look similar: a full package that usually includes a promissory note, a deed of trust, the Closing Disclosure, an occupancy affidavit, and a notice of right to cancel.
What makes a refinance different from a purchase is what happens after you sign. If the home is your primary residence, you get three business days to change your mind, and the loan does not fund until that period ends. That is why refinance signings are dated carefully — the date you sign starts the clock. A cash-out refinance follows the same rule, and your cash arrives only after the waiting period.
Refinances are the most common signing we handle for homeowners in Denver, Lakewood, and Littleton. They rarely surprise anyone if you have reviewed your Closing Disclosure first.
HELOC Signings
A home equity line of credit lets you borrow against your equity as needed, up to a limit, while keeping your existing first mortgage in place. Because it is a second lien rather than a replacement loan, the package is shorter: typically a credit agreement, a deed of trust securing the line, required disclosures, and a notice of right to cancel. Many HELOC signings take under 40 minutes.
Two things trip people up. First, a HELOC on your primary home carries the same three-business-day right to cancel as a refinance, so the line is not available the day you sign. Second, HELOCs are often arranged directly by a bank or credit union rather than through a title company, so your first contact about scheduling may come from the lender. Either way, the notarization requirements for the deed of trust are the same. A home equity loan — a lump sum rather than a revolving line — signs much the same way.
Reverse Mortgage Signings
A reverse mortgage lets homeowners 62 and older convert part of their home equity into cash, a line of credit, or monthly payments, without making monthly mortgage payments while they live in the home. Most are federally insured Home Equity Conversion Mortgages (HECMs).
Reverse mortgage signings need the most preparation:
- Counseling comes first. HUD requires every HECM borrower to complete a session with a HUD-approved counselor before the loan can proceed. Keep your counseling certificate handy; the lender will already have a copy.
- The package is long. Expect more documents than a standard refinance, including HUD-specific forms and a payment plan election. Plan for 60 to 90 minutes or more.
- More people may sign. Every borrower signs, and an eligible non-borrowing spouse may need to sign certain documents too. The title company will tell you who needs to attend.
- Family can be present. Many borrowers like an adult child in the room for support. They can listen, but cannot sign for you unless legally authorized, and the notary will speak with the borrower directly.
Because the stakes are high and the documents unfamiliar, reverse mortgage signings reward a patient, experienced agent. Ask your title company whether the agent they assign handles reverse mortgages regularly — or request one who does.
The Right to Cancel: Which Signings Have It
“This right gives you three business days to cancel a non-purchase money mortgage agreement.”
“Non-purchase money” means a loan that is not used to buy the home — refinances, HELOCs, home equity loans, and most reverse mortgages on a primary residence. Purchase loans do not have this right. The key details:
- The clock: three business days, counting Saturdays but not Sundays or federal holidays.
- The start: the clock begins only after you have signed, received your Truth-in-Lending disclosure (usually the Closing Disclosure), and received two copies of the notice of right to cancel.
- Waiving it: possible only for a genuine personal financial emergency, with your own signed, written statement — not a pre-printed form.
A signing agent will point out the notice of right to cancel in your package but cannot advise you on whether to use it.
Refinance, HELOC, or reverse mortgage — we sign them all.
MJ Notary Denver comes to your home anywhere in the metro, on your schedule, with the patience a reverse mortgage signing deserves.
Book a Signing With MJ Notary Denver
MJ Notary Denver is a certified loan signing agent and National Notary Association member handling refinance, HELOC, reverse mortgage, purchase, and seller signings. Packages start at $100, plus a travel fee starting at $45. See our loan signing packages, learn how we work with your title company, or call (720) 333-0580. We serve Denver, Aurora, Lakewood, Centennial, Littleton, Englewood, and Commerce City.
Frequently Asked Questions
What is the difference between a refinance and a HELOC signing?
A refinance replaces your existing mortgage, so the package is longer and usually takes 45 to 60 minutes. A HELOC adds a line of credit while your first mortgage stays in place, so the package is shorter, often under 40 minutes. Both have a three-business-day right to cancel on a primary home.
Does a HELOC need to be notarized?
Yes. A HELOC is secured by a deed of trust on your home, and that deed of trust must be notarized before it can be recorded with the county. Your lender or title company will arrange a notary or signing agent for the signing.
Can I cancel a refinance after signing?
On a primary residence, usually yes. Federal law gives you three business days after signing to cancel a refinance, HELOC, or other non-purchase loan, for any reason. Saturdays count as business days; Sundays and federal holidays do not.
Do I need counseling before a reverse mortgage signing?
Yes. HUD requires every HECM reverse mortgage borrower to complete a session with a HUD-approved counselor before the loan can move forward. The counseling covers costs, alternatives, and obligations so you can make an independent decision.
How long does a reverse mortgage signing take?
Plan for 60 to 90 minutes or more. Reverse mortgage packages are longer than standard refinances and include HUD-specific forms, and borrowers often want to read them carefully. An experienced signing agent will move at your pace.
Sources: Consumer Financial Protection Bureau, right of rescission and waiver guidance; U.S. Department of Housing and Urban Development, HECM borrower requirements. Last reviewed October 2026.
Written by
MJ Notary Denver
MJ Notary Denver is a certified Colorado notary public and member of the National Notary Association, providing mobile notary, apostille, online notarization, and loan signing services throughout the Denver metro area since 2019. Commission #20194021878.